
8 Ways Insurance Deductibles Surprise Minnesota Residents After a Claim

Homeowner insurance complaints to Minnesota’s Department of Commerce more than doubled in three years, from 569 in 2020 to 1,185 in 2023.
A deductible is behind a lot of them.
It reads like fine print on the declarations page, right up until a claim turns it into the biggest number on the bill.
These are the ways insurance deductibles surprise Minnesota residents after a claim.
Note: This is general information, not insurance advice. Deductible terms and coverage details are subject to change, so confirm the specifics with the Minnesota Department of Commerce.
1. Your Wind and Hail Deductible
A separate wind and hail deductible is standard on many homeowners policies now, and it doesn’t work like the rest of the policy.
Minnesota’s Department of Commerce says those complaints rose from 569 in 2020 to 1,185 in 2023, more than doubling in three years.
Other damage on a Minnesota policy usually answers to one flat number that the declarations page lists in plain print, something like $1,000 or $2,500.
Wind and hail don’t follow that number in many Minnesota policies.
The department has also said some insurers instead charge a flat rate or a percentage of the home’s insured value.
That percentage commonly runs from 1 percent to 5 percent, according to the Insurance Information Institute, and it applies before wind and hail coverage kicks in.
On a $400,000 home with a 2 percent deductible, that comes to $8,000 out of pocket before the insurer pays a cent, using the department’s example.
It often runs double.
The Math Behind a Minnesota Wind and Hail Deductible
A Minnesota home insured for $350,000 with a 1 percent wind and hail deductible owes $3,500 before the insurer pays a claim.
Raise that deductible to 5 percent on the same home, and the number jumps to $17,500.
A standard $1,000 flat deductible never moves no matter what the home is worth, so the percentage version can end up costing far more on a bigger house.
2. Two Storms, Two Deductibles
Minnesota’s wind and hail deductible resets with every separate storm, not once a year the way a health plan’s deductible does.
The Insurance Information Institute says a homeowners deductible applies per claim, not on an annual basis.
That catches people off guard.
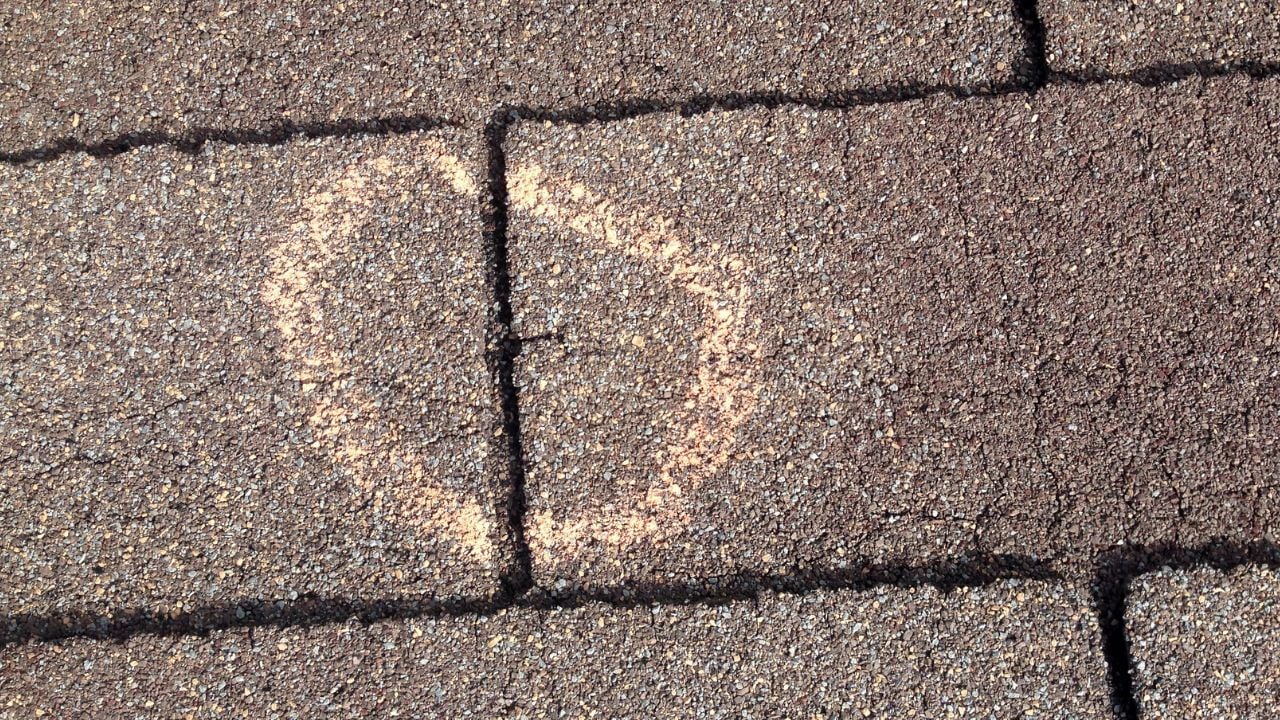
A supercell dropped hail more than two inches wide on northern St. Paul on June 19, 2026.
The National Weather Service logged more than ten minutes of hail falling that day in parts of the area.
Storms like that one rarely arrive just once in a Minnesota summer.
Get hit twice in the same season, and the wind and hail deductible applies in full both times, never split or prorated between the two claims.
3. A Short First Check
Minnesota insurers subtract a homeowner’s deductible from a hail or wind claim twice, not once.
Many insurers pay this kind of claim in two pieces, not one lump sum.
The National Association of Insurance Commissioners describes that split as standard for post-disaster property claims.
The first check covers the actual cash value of the damage, minus the deductible.
Actual cash value means replacement cost minus depreciation for the roof’s age and condition, so the deductible comes off a number that’s already shrunk.
Two holdbacks, one check.
The Hartford calls that second payment recoverable depreciation.
That payment only arrives once repairs are finished and the homeowner sends in receipts or a paid invoice.
Skip the receipts, and that second payment never arrives.
Insurers usually attach a deadline to that second payment too, often six months to a year depending on the state and the policy.
4. The Sewer Backup Exclusion
Sewer backup and a failed sump pump don’t trigger a deductible at all because a standard homeowners policy excludes them from coverage entirely.
Neither flood insurance nor a typical homeowner’s policy covers that kind of water damage, Minnesota’s Department of Commerce says.
Nothing is owed.
There’s no deductible to apply because there’s no coverage to apply it against in the first place.
Coverage only shows up if a homeowner buys a separate sewer backup endorsement.
That endorsement carries a deductible and a coverage limit set apart from the rest of the policy.
A homeowner who assumes the regular deductible covers a flooded basement from a backed-up drain is usually working from the wrong policy entirely.
5. A Different Policy for Flood
Flood damage in Minnesota follows a completely different rulebook than wind or hail claims do.
A standard homeowner’s policy in Minnesota doesn’t provide flood coverage at all, according to the department, so river or surface flooding sits completely outside whatever deductible the declarations page lists.
There’s no fallback.
The only way to add flood coverage is a separate National Flood Insurance Program policy or a private flood policy.
A homeowner buys either one on its own and picks the deductible separately from anything on the homeowners policy.
A homeowner near the Mississippi or Red River who skips that separate policy learns the truth the hard way, after water is already in the basement.
No coverage exists under the standard policy, so no deductible, regular or otherwise, was ever going to apply.
6. The Windshield Deductible
Minnesota drivers often assume a cracked windshield never costs a deductible, but that’s only true for a small chip repair, not a full replacement.
Many insurers waive the deductible for a chip repair as standard practice.
A full replacement is a different story in Minnesota.
State law lets an insurer’s full glass coverage option waive the comprehensive deductible entirely for repairing or replacing damaged safety glass.
That waiver only applies when the driver elected the option ahead of time.
It doesn’t happen by default.
Without that election, the insurer treats a full windshield replacement like any other comprehensive claim, deductible included, no matter how small the original chip looked.
A driver who never elected full glass coverage finds that out the same week the windshield finally gives out.
7. One Storm, Two Bills
A single Minnesota hailstorm can trigger two separate deductibles at once, one on the house and one on the car in the driveway.
Homeowners and their vehicles answer to two completely separate insurance policies.
A hailstorm that dents a roof and pockmarks a car parked in the driveway files as two claims.
One claim goes against the homeowners policy, and the other goes against the auto policy’s comprehensive coverage.
Each policy keeps its deductible.
Paying the home deductible doesn’t reduce or replace what’s owed on the auto side.
The reverse holds too.
Two claims, two deductibles: That’s the total a Minnesota household pays after a bad storm, never a shared number.
Psst! How much do you know about how an insurance claim works? Take our quiz and see if you can ace it.
Quiz
Insurance Claims IQ
Answer these questions on how insurance claims work behind the scenes. We bet you can’t get them all right. Prove us wrong?
Under Minnesota law, how quickly must an insurer acknowledge that it received a claim?
8. No Contractor-Paid Deductibles
A Minnesota law blocks contractors from paying a customer's insurance deductible as a way to win storm-repair work.
State law bars a contractor from paying, waiving, or offering anything of value tied to a deductible as an inducement to sign a repair contract.
Minnesota's Department of Labor and Industry can fine a violator up to $10,000 per violation.
No exceptions apply.
That kind of pitch counts as the exact inducement Minnesota's law was written to stop, not a discount a homeowner is lucky to find.
Minnesota Statute 325E.66 is the law that makes the offer illegal, not an industry guideline or a Better Business Bureau standard.
The $10,000-per-violation fine falls on the contractor who makes that offer, not on the homeowner who hears it.
7 States That Won't Touch a Penny of Your Retirement Income in 2026
Retire to Anchorage, and Alaska hands residents something no other state bothers with, a yearly check just for living there.
Pair that with a state that never touches a pension, a 401(k) withdrawal, or a Social Security check, and retirement income math looks different depending on the address.
7 States That Won't Touch a Penny of Your Retirement Income in 2026
