
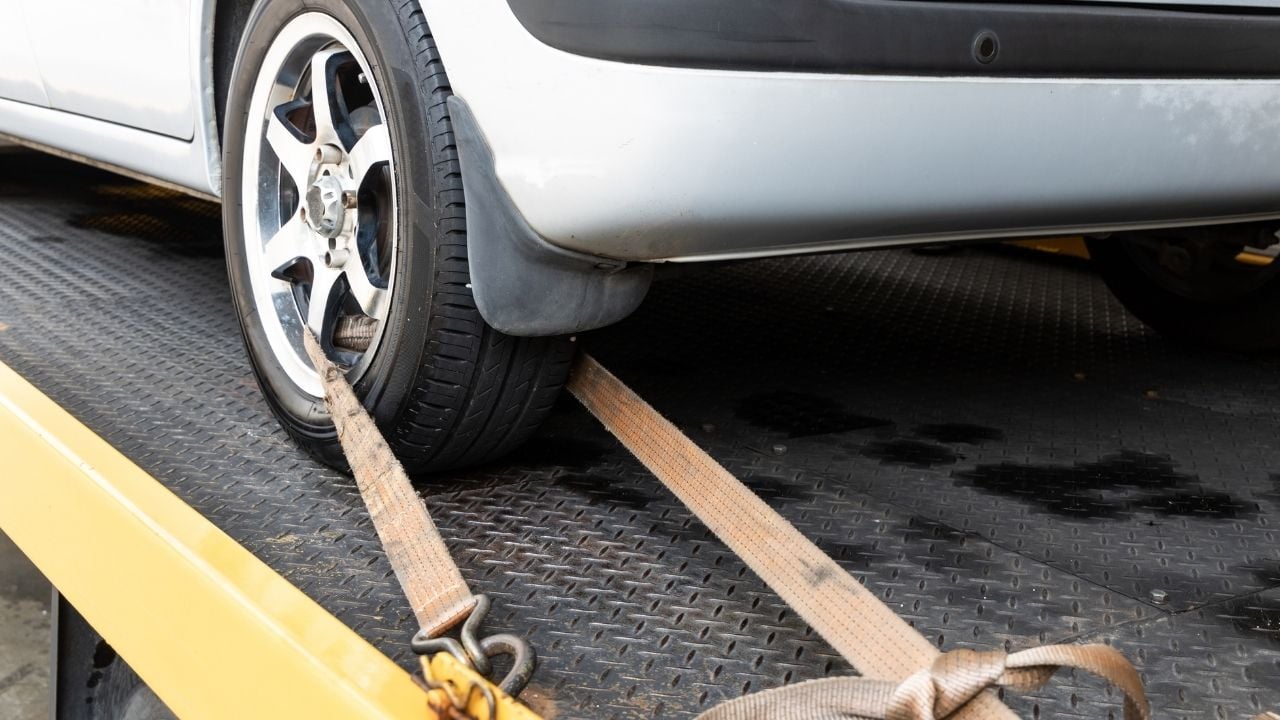
What Happens After Your Car Is Repossessed in Georgia?

Georgia carries the third-highest share of delinquent auto loans in the country, according to a 2025 LendingTree analysis of borrower credit reports.
After a repossession in Georgia, the lender starts a set of legal clocks, and they decide how much more this costs you.
The car is only where it starts.
Note: This is general information, not legal advice. Repossession rules, notice periods and deadlines are subject to change, so confirm the current requirements with the Georgia Attorney General’s Consumer Protection Division.
The Lender Must Mail Notice of the Repossession Within 10 Days
Only two states carry a higher share of delinquent auto loans than Georgia, per LendingTree’s 2025 analysis of borrower credit reports.
Repossession is a pattern a lot of Georgians live through.
Lenders don’t have to warn you before taking the car in Georgia, but state law does require something afterward.
The lender has to send that notice within 10 days of the repossession, by registered or certified mail or statutory overnight delivery, if it ever wants to pursue a deficiency balance later.
Skip that step, and the lender forfeits the right to chase you for anything left owing.
The notice has to spell out two rights in plain terms: Your right to redeem the car, and your right to demand a public sale instead of a private one.
If you miss it, you miss your options.
You then have 10 days after that notice arrives to demand a public sale in writing, sent the same trackable way the lender used.
Your Belongings Get a 60-Day Window
Georgia doesn’t let a lender simply toss whatever’s left inside the car.
The state’s Attorney General Consumer Protection Division says the company has to notify you about your belongings within 10 days of the repossession, then give you 30 days to respond.
No response, and a second notice adds another 30 days before the company can get rid of your things.
That’s up to 60 days total, not an afternoon.
Car seats count too.
Redemption Means Full Payment
Georgia gives you a chance to get the car back before the lender sells it, but the price is steep.
Redeeming that car under Georgia law means paying the entire remaining loan balance, plus the lender’s reasonable repossession costs and attorney’s fees, all at once.
Not just the missed months.
Georgia has no separate reinstatement law that lets you catch up only the overdue payments and walk away with the car, so full payoff is the only guaranteed path.
That right lasts until the lender sells the car or signs a contract to sell it, whichever comes first.
Georgia’s Redemption Math
Redeeming a repossessed car in Georgia costs more than many people expect.
A $9,000 remaining loan balance, plus a $400 repossession fee and any late charges already on the account, adds up to the full number due, not the two or three payments that triggered the default.
Some lenders offer reinstatement anyway as a courtesy.
Nothing in Georgia law requires that choice, so ask early and get any offer in writing.
Psst! How much do you know about Georgia’s title and licensing rules? Take our quiz and see how many you get right.
Quiz
Georgia Titles and Tags Quiz
Answer these questions on Georgia’s title, tag and licensing rules. We bet you can’t get them all right. Prove us wrong?
How old does a car have to be before Georgia drops the title requirement?
No Auction Required
Georgia law sets a floor, not one exact method, for how the lender gets rid of the car.
Every part of that sale, the method, timing and terms, has to be commercially reasonable, whether it happens at a public auction or a private sale.
Reasonable, not necessarily loud.
You can force a public sale by demanding one in writing within that same 10-day window covered above.
The lender then picks the location: Where you live, where the car was repossessed, or where you originally bought it.
Skip that demand, and a private sale is just as legal as a public one.
A Deficiency Balance Can Follow You
Georgia doesn't wipe your debt clean just because the lender took the car back.
If the sale price doesn't cover what you owed plus repossession costs, the lender can pursue you for the difference, known as a deficiency balance.
The debt doesn't vanish.
Georgia law requires the lender to send a written explanation of exactly how it calculated that number, either automatically before it first demands payment or within 14 days if you ask for one.
No explanation, no valid demand.
Psst! How much do you know about your own credit file? Take our quiz and see if you can ace it.
Quiz
Georgia Credit File Quiz
Answer these questions on credit reports, loans and Georgia's own money rules. We bet you can't get them all right. Prove us wrong?
How long can a repossession sit on your credit report before it has to come off?
A Four-Year Window to Sue
Georgia treats a repossession that crosses certain lines as a "breach of the peace," and that opens up recourse.
Courts in Georgia have found an agent crosses that line by forcing entry, using or threatening violence, or continuing after a clear objection.
That's not a gray area.
Georgia law gives you four years from a wrongful repossession to sue over it, the same limit the state applies to any claim for wrongfully taken personal property.
Wait past that window, and the claim is gone no matter how clear-cut it was.
Bankruptcy Freezes the Whole Process
A Georgia bankruptcy filing stops every repossession step cold, no matter where in the timeline you are.
The moment a Chapter 7 or Chapter 13 petition is filed, the federal automatic stay kicks in and halts the sale, the deficiency demand, and any collection call already in motion.
Everything pauses immediately.
A Chapter 13 plan can even let you keep the car and catch up the balance over several years, something Georgia's redemption rule alone doesn't offer.
The lender can ask a judge to lift the stay, but nothing moves again until that happens.
Psst! How much do you know about Georgia's legal records system? Take our quiz and see how many you can get right.
Quiz
Georgia Records Pop Quiz
Answer these questions on Georgia courts, liens and the REAL ID law. We bet you can't get them all right. Prove us wrong?
Georgia centralized Uniform Commercial Code (UCC) lien filings statewide with a 1993 law, ending a system that required lenders to file in all 159 counties. Which kind of property was never part of that system because a separate title-based law covers it instead?
FAQ
Quick answers to what Georgians ask most about what happens after a repossession.
Can a Georgia repo company come onto your property to take the car?
Generally yes, as long as it doesn't force entry, break a lock, or confront you physically. Crossing that line turns a legal repossession into a breach of the peace and opens the door to a lawsuit.
How long do you have to get your belongings back after a Georgia repossession?
Up to 60 days. The company has to notify you within 10 days of the repossession, then give you 30 days to respond, with a second notice adding another 30 if you don't.
Do you have to pay off the whole loan to get your car back, or just the missed payments?
The whole loan. Georgia's redemption right requires paying the full remaining balance plus reasonable repossession costs, not just the payments that were overdue.
Can a Georgia lender come after you for a deficiency balance?
Yes, if the sale doesn't cover what you owed. The lender has to send a written explanation of how it calculated that balance before or when it first asks you to pay.
How long do you have to sue over a wrongful repossession in Georgia?
Four years from the repossession, the same statute of limitations Georgia applies to any claim for wrongfully taken personal property.
Georgia splits bankruptcy filings across three federal court districts, Northern, Middle, and Southern, and which one hears a case depends on the county where the filer lives.
A repossession company that shows up anyway after a stay is filed can face consequences in that same court, not just a stern letter.
6 Georgia Toll Fees That Catch Drivers by Surprise
Georgia's toll roads have a way of finding drivers who thought they'd paid everything already.
One fee in particular catches even longtime metro Atlanta commuters off guard.
6 Georgia Toll Fees That Catch Drivers by Surprise
9 Waffle House Rules Most Non-Georgians Have No Idea Exist
Georgia is Waffle House's home state, with more locations there than anywhere else, and that density built its own unwritten etiquette.
Order it wrong, and regulars will clock you as an out-of-stater fast.
