
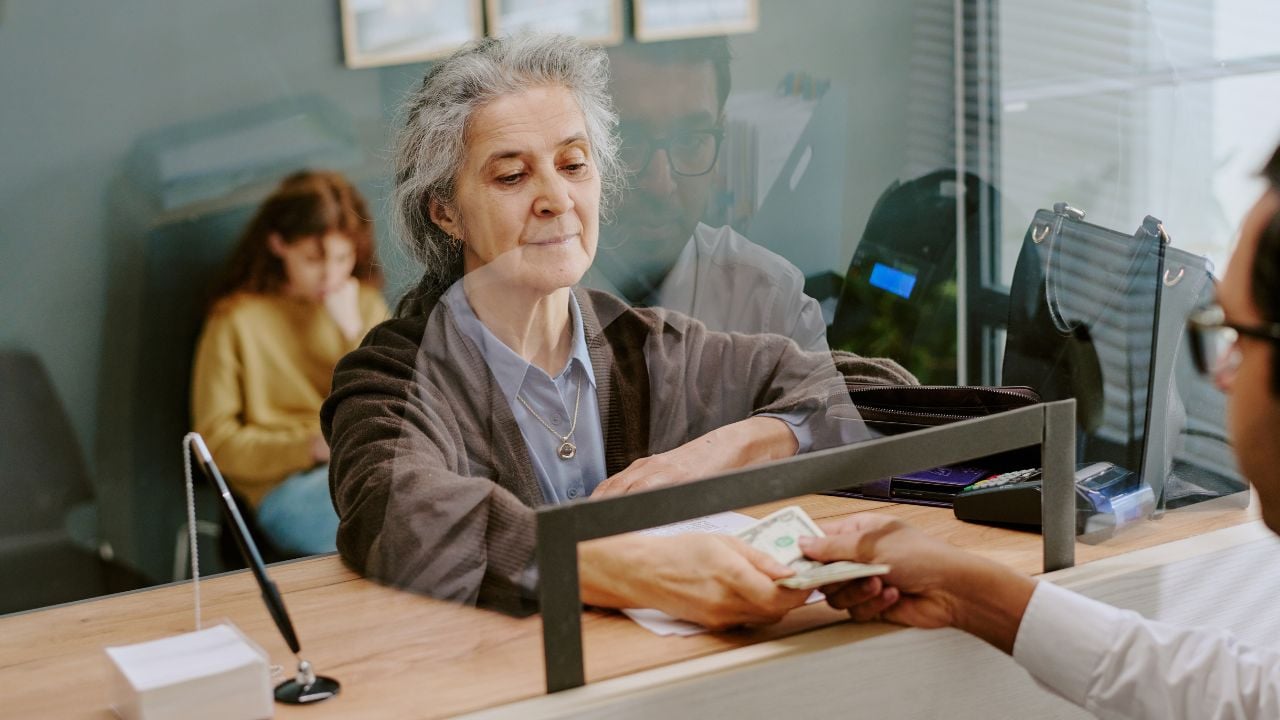
11 Transactions That Immediately Raise a Red Flag for Georgia Bank Tellers

A Georgia bank can’t sell a cashier’s check, money order, or traveler’s check for $3,000 or more in cash without stopping to record who’s buying it.
Three thousand dollars isn’t a lot of money.
These are the transactions that immediately raise a red flag for Georgia bank tellers.
Note: This is general information, not legal or financial advice. Federal reporting thresholds and Georgia’s banking protections are subject to change.
1. Cash Near $10,000
A bank teller starts paying closer attention the moment a cash transaction gets near $10,000.
Federal law requires every bank and credit union to file a Currency Transaction Report on any cash deposit, withdrawal, or exchange of currency over $10,000 in one business day.
That includes several smaller transactions on the same day that add up past the line.
The teller isn’t guessing.
They ask for a Social Security number and a government ID the moment the total crosses the threshold, even for a longtime customer.
The $10,000 line hasn’t moved since 1972, and it applies the same way in Macon as it does in Manhattan.
2. Splitting One Deposit in Two
A bank catches a split deposit the same day it happens, no second visit required.
Federal rules add up every cash transaction at a bank on the same business day, no matter which teller worked the counter or what time it happened.
A customer deposits $7,500 with one teller in the morning, then comes back that same afternoon to deposit another $7,500 with someone else.
By closing time, that customer has already crossed the reporting line.
Federal law calls this structuring, and it’s a crime whether or not the cash itself came from anywhere illegal.
FinCEN publishes that same-day scenario as a textbook example of what evasion looks like.
It happens often.
Prison time is on the table, and so is a fine, even when every dollar involved is completely legal.
3. Checks Just Under $10,000
A bank can’t sell a cashier’s check, money order, or traveler’s check for $3,000 or more in cash without stopping first.
The teller has to collect a name, a Social Security number, and a form of government ID right there at the counter before the sale goes through.
Federal rules set that $3,000 to $10,000 window because it’s the range where structuring through checks tends to show up.
Above $10,000, it becomes a full Currency Transaction Report instead.
A retiree who walks in with $8,000 cash and asks for a single cashier’s check hits that window in one visit.
No second trip required.
The bank combines multiple same-day purchases that add up to $3,000 or more into one record too, the same way it does with cash deposits.
4. Wiring Money in Small Chunks
A bank counts a wire paid for in cash the same way it counts any other cash transaction.
The bank folds that wire into its daily cash total, right alongside deposits and check purchases.
A customer who pays cash for several wires in one visit can cross $10,000 before lunch.
Spreading those payments across the same afternoon doesn’t reset the count.
Federal law calls that structuring, the same wire version of splitting a deposit into two trips.
The penalties match too.
Prison time is on the table.
So is a fine, even when the money itself is clean.
5. Big Withdrawal From a Dormant Account
A bank pays attention the moment a long-dormant account produces one large withdrawal.
An account that’s sat untouched for years doesn’t need a string of activity to earn a second look.
One big withdrawal does the job on its own, right after years of nothing.
Timing is what matters.
FinCEN’s advisory on elder financial exploitation names a dormant account with a large balance that suddenly shows a withdrawal as one of its clearest financial red flags.
Banks filed more than 72,000 suspicious activity reports tied to elder exploitation in 2021 alone.
A retiree who hasn’t touched an account in years, then withdraws a large sum in a single visit, gets a second look on the spot.
That’s especially true when the balance drops fast.
6. Wiring Someone You’ve Never Met
Wiring money out of a Georgia bank to someone the customer has never met in person is one of the clearest patterns FinCEN tracks.
Romance scams alone cost victims $547 million in reported losses in 2021, per FinCEN, and many of those payments moved out through an ordinary wire at an ordinary bank branch.
A teller doesn’t need proof of a scam to flag the wire.
The pattern alone is enough.
A customer sending money interstate or overseas to someone they can’t fully explain, tied to an online friend or a sudden business opportunity, matches a pattern FinCEN has named directly.
The teller just has to notice it first.
7. Stack of Gift Cards
Buying a stack of gift cards at a bank or a nearby store is a pattern tellers are trained to notice, especially from an older customer.
FinCEN names large gift card or prepaid card purchases as a financial red flag tied straight to tech-support scams and government imposter scams.
The codes are the target.
Scammers ask for the numbers on the back because the money moves fast once a code is read over the phone, and it’s almost impossible to get back after that.
A teller asks what the cards are for when a customer buys several at once, especially several hundred dollars’ worth.
8. Small Bills Exchanged for Large Ones
A bank teller notices right away when a customer wants to trade a stack of small bills for large ones.
Federal examiners list that exact swap, small notes exchanged for hundreds, as one of the oldest structuring moves in the book.
A pile of $20s and $50s turns into a slim stack of $100 bills, easier to move and easier to hide.
One visit is enough.
A customer who walks in with several thousand dollars in small bills and asks to trade up doesn’t need a pattern to catch a teller’s eye.
The request alone is enough to trigger extra questions, especially when the amount sits just under the reporting line.
9. Closing a CD Before It Matures
A bank notices when a customer cashes out a certificate of deposit (CD) early and doesn’t blink at the penalty.
Breaking a CD ahead of schedule usually costs months of interest.
FinCEN watches for that.
Its advisory on elder financial exploitation lists closing an account without regard to the penalty as one of its clearest financial red flags.
Every bank employee in Georgia counts as a mandated reporter under the state’s Disabled Adults and Elder Persons Protection Act.
Georgia banks can also place a hold on a transaction like that one for up to 15 business days under House Bill 945, effective July 1, 2026.
The hold covers suspected exploitation of an adult who’s 65 or older or disabled.
What a Suspicious Activity Report Does
A Georgia bank that files a Suspicious Activity Report almost never tells the customer it happened.
Federal law makes that silence mandatory, not rude.
Tipping off the customer is against the law for the bank and the employee who does it.
The report goes to the Financial Crimes Enforcement Network, not straight to a badge at the door.
Investigators decide later whether it’s worth a follow-up call.
Filing one doesn’t accuse anyone of anything.
The report becomes a data point in a file a bank has to keep for five years, whether or not anything ever comes of it.
10. Memo Lines That Spell Out a Scam
The memo line on a check or wire can tip off a bank teller before the transaction even clears.
FinCEN flags checks and wires carrying words like “tech support services,” “winnings,” or “taxes” in the memo line, sent to someone the customer doesn’t personally know.
That combination counts as a financial red flag tied straight to common scams.
Same script, every time.
Scammers coach victims on exactly what to write, right down to the wording that makes the payment look official.
A teller who’s seen the same phrase a dozen times that month knows the drill.
Psst! How much do you know about the history behind your bank? Take our quiz and see how many you can get right.
Quiz
American Banking History IQ
Answer these questions on money, banks, and the history behind them. We bet you can’t get them all right. Prove us wrong?
When did Congress create the FDIC, and what was the original deposit insurance limit?
11. ID That Doesn't Match the Story
Refusing to hand over identification for a large transaction is a red flag at a bank.
Federal rules require a bank to collect a name, address, Social Security number, and a form of government ID for any cash transaction that crosses the reporting threshold.
There's no exception for a familiar face.
Paper trails matter too.
Examiners also tell banks to flag any transaction with no clear lawful purpose.
The same goes for one that doesn't match what the bank already knows about a customer's income, job, or account history.
A retiree who's never moved more than a few hundred dollars a month suddenly wiring thousands overseas doesn't need to break a rule to earn a second look.
The mismatch is often enough on its own.
7 Kroger Perks Every Georgia Shopper Should Be Using
Kroger checks out more than 11 million customers a day, and many of them are Georgians who never redeem everything sitting on their account.
A few small habits at the register turn routine trips into extra savings.
7 Kroger Perks Every Georgia Shopper Should Be Using
8 Medicare Enrollment Mistakes That Cost Georgia Retirees All Year
A missed Medicare deadline can follow a Georgia retiree for years, tacking a permanent surcharge onto a premium that never goes back down.
One overlooked enrollment window is often all it takes, and the same mistakes turn up again and again among retirees who assumed Medicare worked like Social Security's rules.
8 Medicare Enrollment Mistakes That Cost Georgia Retirees All Year
