
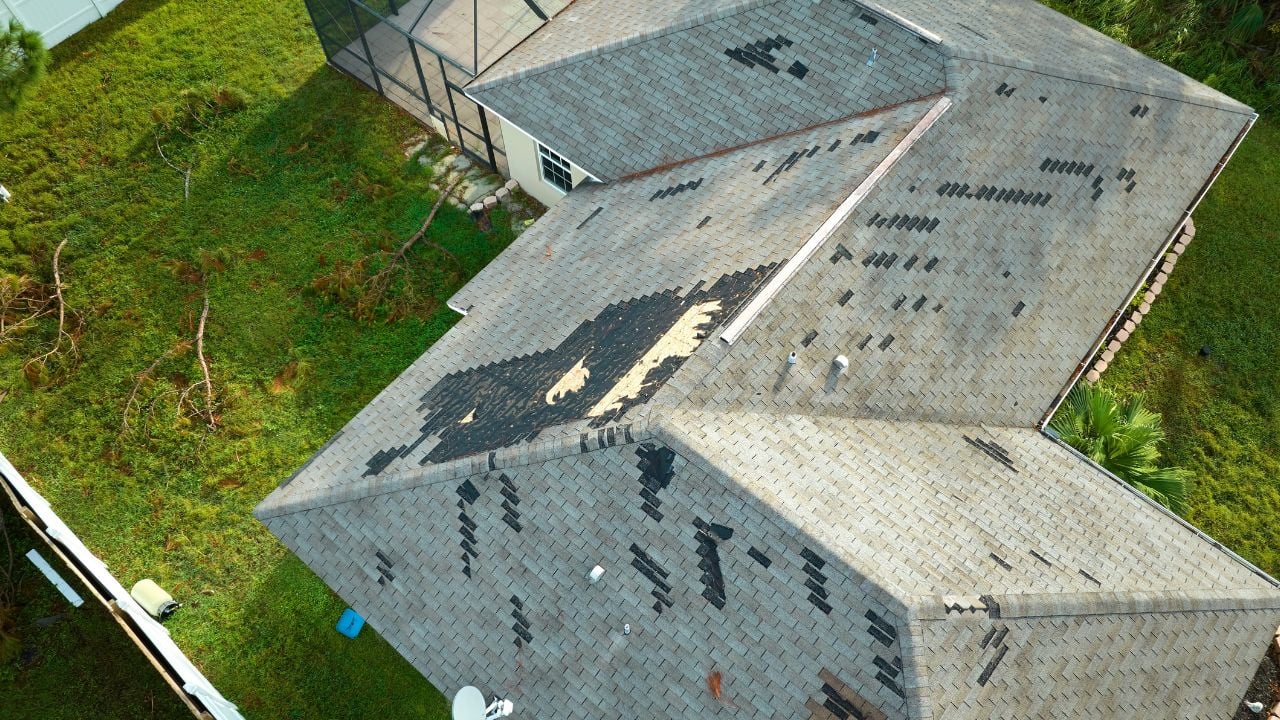
Why Do South Carolina Homeowners Insurance Rates Keep Rising?

South Carolina’s average homeowners premium jumped 20% in 2025, from $2,581 to $3,092.
That’s an extra $511 in twelve months, according to the marketplace Insurify.
Rates keep climbing because insurers in South Carolina paid out $1.44 for every premium dollar they collected in 2024, a combined ratio of 143.9%.
Reinsurance, a shrinking bench of private carriers, lawsuit costs, and pricier rebuilds are all pulling in the same direction.
Note: This is general information, not insurance advice. Rate filings and coverage rules change, so confirm current details with the South Carolina Department of Insurance.
How Much Have South Carolina’s Rates Gone Up?
That 20% jump took the state’s average policy from $2,581 to $3,092 a year.
That’s an extra $511 on a single policy in twelve months.
It didn’t stop at one jump, either.
South Carolina’s increase was the sixth-largest in the country last year.
Only Minnesota, Colorado, Iowa, Nebraska, and Oklahoma rose faster.
Every other state rose slower.
South Carolina’s rates aren’t projected to level off in 2026, either.
Insurify projects another 9% increase this year, pushing the average policy toward $3,370.
Why Does Reinsurance Cost So Much in South Carolina?
South Carolina’s home insurers spent 2024 paying out far more than they collected.
The industry’s combined ratio for homeowners’ coverage in South Carolina hit 143.9% that year, meaning insurers paid out $1.44 for every dollar of premium they took in.
That ratio hadn’t been anywhere close to that for years.
It sat at 78.5% in 2021, rose to 94.8% in 2022, and eased back to 88.2% in 2023.
Then 2024 wiped out three years of underwriting gains in a single season.
South Carolina wasn’t spared from that year’s storms, and reinsurers charge insurers more every time a hurricane season gets expensive anywhere near the coast.
Insurers pass that reinsurance bill on to every policyholder, not just policyholders who filed a claim.
That’s why a homeowner with no storm damage and no claims history can still watch a renewal price rise.
What a Combined Ratio Measures
South Carolina’s 143.9% combined ratio bundles two separate costs together.
One piece is claims paid to policyholders after storms, fires, and other covered losses.
The other piece is the insurer’s operating expenses, including the reinsurance it buys to protect the company.
A ratio under 100% means an insurer is turning an underwriting profit on its policies before investment income.
A ratio that stays above 100% for several years running is what pushes insurers toward bigger rate requests, or toward writing fewer new policies in a state.
What Is the South Carolina Wind and Hail Underwriting Association?
The South Carolina Wind and Hail Underwriting Association spreads its storm losses across every property insurer in the state, so a bad hurricane season along the coast raises costs statewide, not just for companies writing beachfront policies.
State lawmakers created the pool, often called the Wind Pool, back in 1971 because private insurers wouldn’t fully cover coastal wind risk on their own.
Every property insurer doing business in South Carolina is required to help fund it.
The Wind Pool covers wind and hail damage inside the legislatively defined coastal “Beach” territory, for homeowners who can’t find that coverage in the standard market.
It’s a market of last resort, not a bargain.
A single-family home can carry up to $1.3 million in Wind Pool coverage for the structure, contents, and loss of use combined.
Psst! How much do you know about South Carolina’s hurricane history? Take our quiz and see how many you can get right.
Quiz
South Carolina Hurricane History IQ
Answer these questions on South Carolina hurricanes and coastal geography. We bet you can’t get them all right. Prove us wrong?
What category was Hurricane Hugo when it made landfall near Sullivan’s Island in 1989?
Are Insurance Companies Leaving South Carolina?
Some insurance companies have pulled back from South Carolina, or stopped writing new policies altogether, after years of weather losses and fraud costs.
State officials point to that shrinking pool of carriers as one reason remaining insurers can raise prices with less pushback.
Fewer companies competing for a homeowner's business means fewer companies racing each other on price.
South Carolina lawmakers have been studying the problem directly.
A state House committee spent 2025 hearing testimony on why rates keep rising, and it led to a bill called H.4817, the Insurance Rate Reduction and Policyholder Protection Act, still moving through the state Senate as of this year.
Insurance fraud came up in that same testimony, too.
A National Insurance Crime Bureau presentation to South Carolina lawmakers found questionable roofing claims tied to storm damage jumped 90% in 2024.
That jump adds another cost that gets built into everyone's premium.
Add it up, and a shrinking list of insurers plus a rising list of disputed claims gives South Carolina's remaining carriers less reason to compete on price.
How Do Lawsuits Affect South Carolina's Rates?
South Carolina lawmakers passed a major tort reform law in 2025 aimed partly at litigation costs tied to rising insurance premiums.
Gov. Henry McMaster signed the tort reform and liquor liability bill into law in May 2025, with most of its changes taking effect at the start of 2026.
Lawsuits and large jury verdicts raise an insurer's expected cost of doing business in a state.
Insurers build that expectation into premiums before a single storm ever forms.
It's baked in, whether or not a policyholder ever files a claim.
The new law changes how liability gets divided among multiple defendants and tightens the insurance rules around alcohol-related liability.
Insurers and lawmakers blamed both areas for driving up costs.
Why Does It Cost More to Rebuild in South Carolina?
Rebuilding a storm-damaged home in South Carolina costs more today than it did just a few years ago.
Severe or extreme wind risk is the kind of exposure that defines coastal South Carolina.
Homes in those areas carry premiums about 58% higher than similar homes with a medium level of wind risk.
A federal report published in February 2026 found that gap between wind-risk levels.
That works out to roughly $1,294 more a year on the same house, just for sitting in a higher wind zone.
Add the price of shingles, lumber, and contractor labor, and every rebuilt roof costs an insurer more than the one it replaced.
Insurers pass that math straight through to renewal notices.
Will South Carolina's Rates Keep Rising?
South Carolina's home insurance costs are still heading up, according to current industry forecasts.
Insurify projects South Carolina's average premium will rise another 9% in 2026, adding roughly $278 to the typical policy.
That would put the average South Carolina homeowner near $3,370 a year.
Two straight years of double-digit or near-double-digit jumps is what a multi-year trend looks like.
It's not a one-time correction.
Lawmakers are betting the new tort law and the pending rate-reduction bill will eventually slow that trend.
Neither one changes a renewal notice that's already sitting in a South Carolina mailbox this year.
Psst! See how South Carolina's rate jump stacks up against the rest of the country in the table below.
FAQ
South Carolina homeowners frequently search these questions about rising insurance costs.
Why are South Carolina homeowners insurance rates going up?
South Carolina rates are rising because insurers paid out more in claims and reinsurance than they collected in 2024, pushing the state's homeowners combined ratio to 143.9%.
Rebuilding costs, a smaller pool of competing insurers, and litigation costs add to the pressure.
Is South Carolina's increase bigger than other states'?
Yes. South Carolina's 20% jump in 2025 was the sixth-largest increase in the country, behind only Minnesota, Colorado, Iowa, Nebraska, and Oklahoma.
Does South Carolina have a FAIR Plan for homeowners who can't get coverage?
South Carolina doesn't run a separate FAIR Plan.
Its insurer of last resort is the Wind and Hail Underwriting Association, and that pool only covers wind and hail damage in the coastal Beach counties.
Fire, theft, and other perils a standard homeowners policy covers stay outside the Wind Pool.
Is South Carolina doing anything to slow the rate increases?
State lawmakers are weighing a bill that would let South Carolina's Department of Insurance take over fraud investigations and increase criminal penalties for insurance fraud.
The bill's goal is removing some of the cost drivers behind the increases.
9 South Carolina Roadside Stands Locals Stop at and Tourists Drive Past
A folding table of boiled peanuts sits on the shoulder of a South Carolina backroad, and many drivers never slow down for it.
The locals who do stop already know which stands are worth the detour.
9 South Carolina Roadside Stands Locals Stop at and Tourists Drive Past
7 Charges on Every South Carolina Power Bill That Have Nothing to Do With Electricity
A South Carolina power bill carries more line items than many homeowners ever read past the total.
Several of them have nothing to do with how much electricity got used.
7 Charges on Every South Carolina Power Bill That Have Nothing to Do With Electricity
