
8 Property Tax Surprises That Hit California Buyers in Their First Year

The house next door is the same house, built the same year, on the same street.
But its tax bill runs lower than yours.
Proposition 13 explains that gap, and explaining it is the last comfortable thing it does for a new California owner.
These are the property tax surprises that hit California buyers in their first year.
Note: This is general information, not legal or tax advice. Assessment rules and exemption amounts are subject to change, so confirm the current details with your county assessor’s office.
1. Owing a Bill Escrow Never Saw
California mails a separate supplemental tax bill to new homeowners.
It has nothing to do with the prorated amount you already settled with the seller at closing.
Escrow only covers what the seller already owed through the day title transferred.
The county’s bill, based on your new assessed value, can arrive three to six months later, mailed straight to you instead of your escrow company.
Few buyers see it coming.
Nobody wires it at the closing table.
That’s the part the closing paperwork never spells out.
2. Paying More Than the Neighbor Next Door
A newly bought home in California can carry a far bigger tax bill than a nearly identical one two doors down.
The gap comes from Proposition 13’s change-of-ownership rule: The county wipes out the seller’s old assessed value and resets it to the exact price you paid, the moment ownership changes.
A longtime owner next door never got that reset, so their number stayed capped at 2% growth a year while yours starts at full market value.
Santa Clara County’s assessor’s office lays out the scale of it.
A home bought years ago for $100,000 can still be assessed near $110,000, while the owner of an identical one bought today pays tax on the full $150,000.
The neighbor didn’t do anything special to earn the lower bill.
They just never moved.
3. Getting Two Supplemental Bills at Once
Buyers who close in California between January 1 and May 31 can end up with two separate supplemental bills for the same purchase.
The first covers what’s left of the fiscal year you bought in.
The second covers the entire next fiscal year, according to Los Angeles County’s property tax office.
That’s two envelopes for one house.
Neither bill is optional.
A buyer who closes escrow in March owes taxes for the rest of that spring, then owes a second bill for the full year that follows.
Ask your escrow officer whether your closing date falls inside that window, so both bills land on your radar instead of just one.
4. Assuming Your Impound Covers It
Lenders in California who collect an impound account for taxes and insurance almost never fold the supplemental bill into it.
Many lenders skip it, according to Tulare County’s tax collector.
The bill goes straight to you, not your mortgage company.
It’s yours alone.
Call your loan servicer directly and ask whether supplemental taxes are part of your impound analysis because assuming yes is how a bill goes unpaid.
A verbal answer isn’t enough; get it confirmed in writing before your first bill even shows up.
Psst! How ready are you for what’s still coming in the mail? Run through this checklist and see where you stand.
5. Watching the Bill Swing With Your Closing Date
Your closing date, not the price you paid, decides how big California’s first supplemental bill runs.
Placer County’s assessor’s office prorates using an example: Close with nine months left in the fiscal year, and the bill lands at three-quarters of the full-year increase.
A July closing can owe nearly the full year’s increase, while a closing the following June owes barely a month’s worth of that same amount.
The exact same purchase can trigger two very different first-year bills.
Nothing else moves that number.
The calendar is the only variable, and nobody negotiates that at the closing table.
6. Missing the Homeowners’ Exemption Deadline
California’s homeowners’ exemption knocks $7,000 off a home’s assessed value for owners who file for it.
The county doesn’t do that automatically.
Riverside County’s assessor office puts the full-year savings at roughly $70, available to anyone who files by February 15.
If you miss that date, you can still recover 80% of it by filing before December 10.
Filing after December 10 forfeits the exemption for that year.
That’s not nothing.
It adds up over a decade of ownership.
That makes it one of the few property tax breaks a first-year buyer has to ask for by name.
The Homeowners’ Exemption’s Faster Deadline
California’s homeowners’ exemption runs on a different clock when it follows a supplemental assessment instead of the regular roll.
File within 30 days of the assessor’s Notice of Supplemental Assessment, and the full $7,000 reduction applies to that bill too, per Placer County’s assessor.
Missing the 30 days still leaves you 80% of it, as long as you file before the first supplemental installment goes delinquent.
7. Discovering a Mello-Roos Line Item
Local districts in California can add a Mello-Roos special tax right on top of the regular 1% rate.
Many newer subdivisions carry one.
Nobody prints Mello-Roos on the for-sale sign.
The charge pays for schools, roads, or fire stations built for the community.
California adds it on top of the 1% rate rather than folding it inside, according to San Diego County’s assessor’s office.
It isn’t capped by Proposition 13’s statewide 2% limit.
Each Community Facilities District (CFD) spells out its maximum allowed increases in the district’s formation documents, the assessor’s office notes.
Check your preliminary title report before you close because a recorded Notice of Special Tax Lien is often the only place the charge turns up.
8. Facing a Penalty With No Warning
Once the due date passes, California treats a supplemental bill exactly like a regular one, penalty included.
The 10% late penalty applies once that date passes, with no grace period.
Not receiving the bill in the mail doesn’t cancel the penalty, either.
California Revenue and Taxation Code Section 2610.5 says a failure to receive a tax bill doesn’t relieve the lien or stop the penalty, as Marin County’s tax office explains.
A regular annual bill runs on familiar dates, due November 1 and February 1, delinquent December 10 and April 10.
Read the notice closely.
A supplemental bill runs on different dates instead, printed right on the notice.
Missing an address update or a late forward won’t undo the penalty once the date passes.
9 California Wildfire Insurance Rules Homeowners Learn Too Late
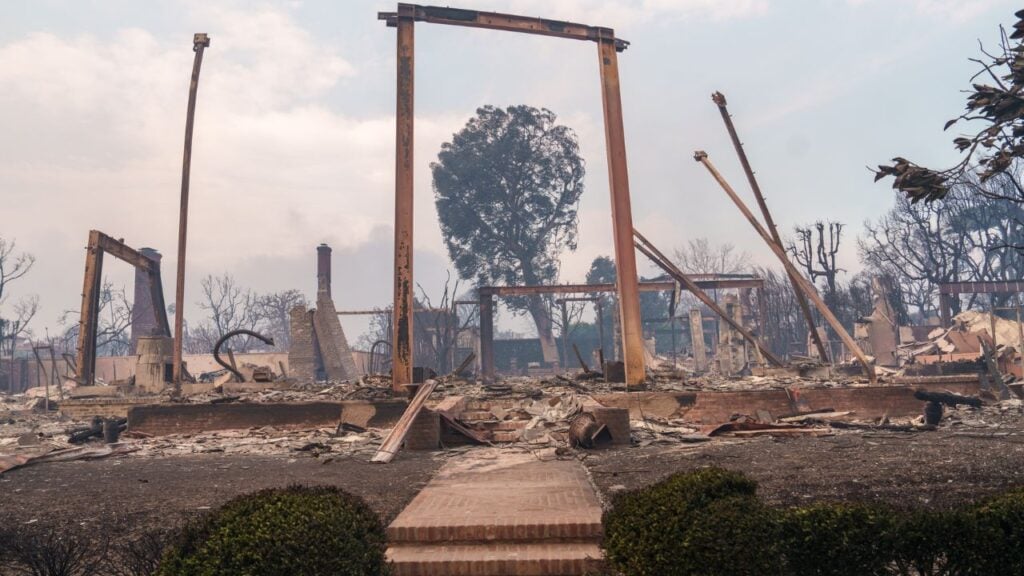
A standard homeowners policy in California doesn’t guarantee wildfire coverage the way many first-year buyers assume.
The state’s Fair Access to Insurance Requirements (FAIR) Plan is California’s insurer of last resort for high fire risk, and it covers fire and little else.
9 California Wildfire Insurance Rules Homeowners Learn Too Late
8 California Lawn and Water Rules Homeowners Get Fined For
California homeowners can face a fine for running a sprinkler at the wrong hour, not just for using too much water.
Local water agencies enforce these rules block by block, and many new owners find out only after a citation arrives in the mail.
