
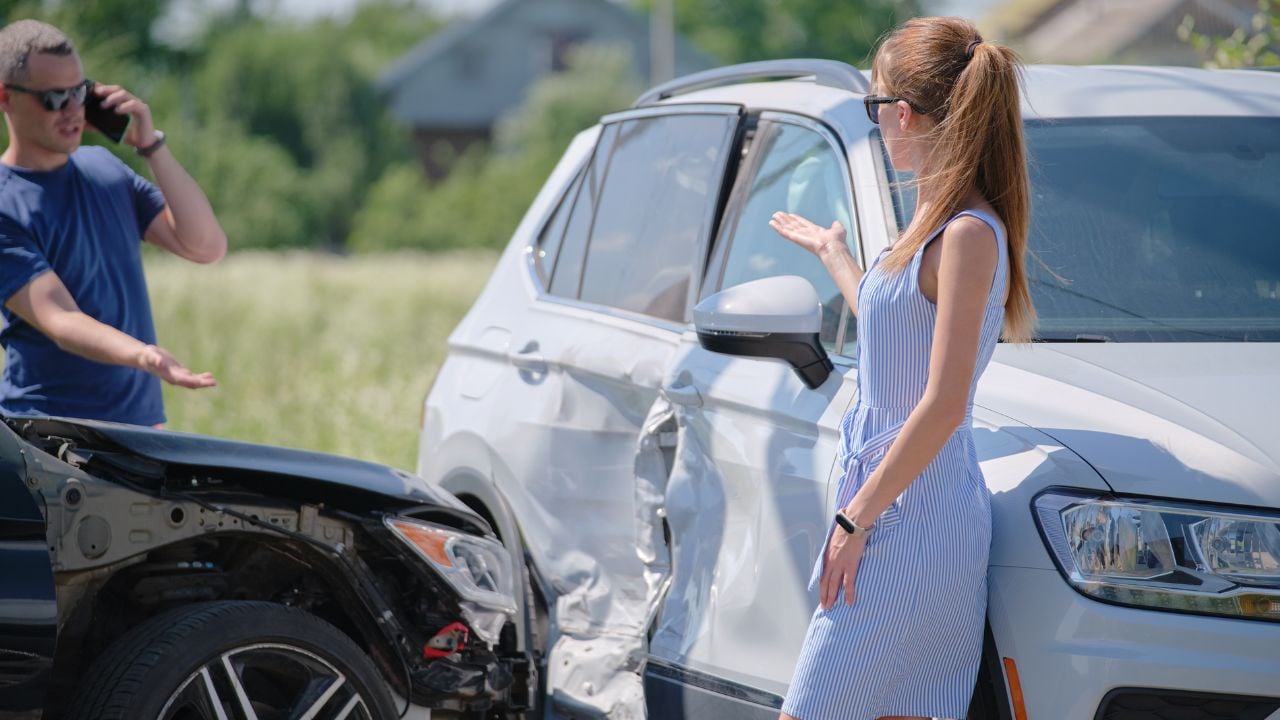
Why Does a South Carolina Car Insurance Premium Jump After a Not-at-Fault Accident?

The other driver caused the crash, so why does your renewal notice say you owe more?
“Not my fault” doesn’t always mean no change to your rate.
Here’s why a South Carolina premium can jump after a not-at-fault accident, and what to check before your next renewal.
Note: This is general information, not insurance or legal advice. Laws and terms are subject to change, so confirm current details with your insurer or the South Carolina Department of Insurance.
How Does a Not-at-Fault Accident Raise Your South Carolina Premium?
Your South Carolina car insurance premium reflects a list of rating factors that includes driving record, location, age, credit history and the coverages and deductibles you choose.
The Consumer Federation of America (CFA), an advocacy group, ran a 2017 study of five large insurers in 10 cities.
Drivers in 8 of the 10 cities could be surcharged after an accident that wasn’t their fault.
One of the five insurers didn’t surcharge in the cities studied.
That’s 10 cities rather than South Carolina as a whole, so treat it as a national finding.
Ask your insurer whether it surcharges for not-at-fault accidents.
State law lets insurers use different filed rates under rating plans the insurance director approves.
A rate increase can’t take effect until the new policy period begins.
If your renewal places you above the lowest tier, the insurer must tell you and give the reason in writing.
A separate state rule limits when an insurer can refuse to renew over accidents, and it doesn’t reach price.
It bars refusal over two or fewer accidents in three years unless you, a household member or another regular driver caused them wholly or partially.
What South Carolina’s 7% Rate Rule Covers
South Carolina lets an insurer’s overall average rate change of up to 7% take effect without prior approval.
The cap doesn’t apply on an individually insured basis.
That makes 7% an average across the insurer’s policyholders, not a ceiling on one driver’s increase.
An insurer can use that approval-free route for one increase in any 12 months.
Who Decides an Accident Wasn’t Your Fault?
A South Carolina car insurer’s fault finding can move your premium, and a 2001 case before the state Supreme Court shows how.
After an internal investigation, the insurer decided its customer was predominantly at fault.
It paid damages to the other driver from her policy and assigned two surcharge points.
Then it notified her that it intended to raise her premium by more than $600.
A second insurer later removed the surcharge and lowered her premium rate after she provided documentation.
The documentation showed the other driver had been convicted of a moving violation in connection with the accident.
That accident happened in 1996, so insurers’ current practices may differ.
Psst! How much do you know about how car insurers rate claims? Take our quiz and see if you can ace it.
Quiz
Premium Pop Quiz
Answer these questions on how car insurers rate claims. We bet you can’t get them all right. Prove us wrong?
Connecticut’s insurance department says what about inquiries on possible coverage when it comes to a CLUE report?
Does a Not-at-Fault Claim Appear on a CLUE Report?
Car insurance claims can land in a claims database called CLUE, short for Comprehensive Loss Underwriting Exchange.
Connecticut's insurance department says a claim where the insurer paid nothing may still appear.
Whether a report notes who was at fault isn't addressed.
Insurers report a claim when they pay out money, set up a file for a possible claim or formally deny one.
Washington's insurance commissioner says LexisNexis generates the report and that it lists the date of loss, the type of loss and the amount the company paid.
A report generally contains up to seven years of personal-auto and personal-property claims.
Because claims history is a rating factor, a copy of your report is worth reading before you shop for new coverage.
The Fair Credit Reporting Act entitles you to a free copy of your CLUE report.
What Two South Carolina Bills Would Change
A Senate bill and a House bill, both introduced Jan. 13, 2026, take on one kind of South Carolina car insurance premium increase.
Uninsured motorist (UM) and underinsured motorist (UIM) coverage helps cover costs if someone with little or no insurance injures you, according to the National Association of Insurance Commissioners (NAIC).
Current state law already requires UM coverage in every South Carolina auto policy.
State law bars an insurer from refusing to renew you solely over a UM claim when the uninsured driver is known or there's physical evidence of contact.
Each bill would bar an insurer from raising a premium solely because an insured made a UM or UIM claim, if the insured wasn't at fault.
Psst! Think you can shop smart for car insurance? Take our quiz and see how you score.
Quiz
Smart Shopper Quiz
Answer these questions on shopping for car insurance. We bet you can't get them all right. Prove us wrong?
In South Carolina, how long after a policy starts can an insurer cancel without cause?
FAQ
Can car insurance go up after a not-at-fault accident in South Carolina?
A 2017 national study found it can, depending on the insurer.
The Consumer Federation of America found drivers in 8 of 10 cities could be surcharged after an accident that wasn't their fault.
One of the five insurers studied didn't surcharge.
Will my insurer tell me why my rate went up?
If your renewal places you above the lowest rate tier, South Carolina law says the insurer must tell you.
The insurer must give the reason for the higher tier in writing.
Can my insurer refuse to renew my policy after a not-at-fault accident?
South Carolina bars an insurer from refusing to renew solely because of accidents older than 36 months.
It bars refusal over two or fewer accidents in three years, unless you, a household member or another regular driver caused them wholly or partially.
How long does a claim stay on a CLUE report?
Washington state's insurance commissioner says a CLUE report generally contains up to seven years of personal-auto and personal-property claims.
You can request a free copy through the LexisNexis Consumer Center.
Does accident forgiveness cover a not-at-fault accident?
The NAIC defines accident forgiveness as an insurer agreeing not to raise your premium after an at-fault accident.
That definition doesn't address a not-at-fault accident, and terms vary greatly, so check your policy.
15 Habits That Give Away a South Carolina Native Within Five Minutes
You can spot a South Carolina native by what they reach for first.
It takes about five minutes.
15 Habits That Give Away a South Carolina Native Within Five Minutes
6 Grocery Staples That Cost South Carolina Shoppers Far More Than in 2005, and 4 Have More Than Doubled
You don't need us to tell you groceries cost more than in 2005.
But how much more?
