
7 Reverse Mortgage Terms That Catch Florida Families Off Guard

Florida placed second in the nation for reverse mortgage lending volume in fiscal year 2023, trailing only California, according to the Federal Housing Administration’s count of Home Equity Conversion Mortgage loans.
That volume means thousands of families sign a stack of federal paperwork every year.
Many never read past the highlights.
These are the reverse mortgage terms that catch many Florida families off guard.
Note: This is general information, not financial or legal advice. Reverse mortgage terms and requirements are subject to change, so confirm the current details with a reverse mortgage counselor approved by the U.S. Department of Housing and Urban Development (HUD).
1. Mandatory Counseling Session
Seniors pursuing a federally insured reverse mortgage face one required stop before anything else moves forward.
Federal rules require every Home Equity Conversion Mortgage (HECM) applicant to meet with an independent counselor before a lender can start the paperwork.
The lender doesn’t pick that counselor.
Independence is the point.
The session walks through the loan’s costs, the alternatives, and what happens later if property taxes or insurance go unpaid.
HUD recommends a $125 fee for the session, though individual counseling agencies can charge less or waive it.
Many families expect a quick phone call.
The session usually runs close to an hour, sometimes longer for someone who has never seen this paperwork before.
2. First-Year Draw Limit
Homeowners who qualify for a large reverse mortgage often assume the full amount is theirs at closing.
It isn’t.
A federal rule caps new HECM borrowers to 60% of their initial principal limit during the first 12 months.
A borrower with a $200,000 principal limit, for example, can access up to $120,000 of it in that first year.
The rest waits.
A family that planned to cover a big bill at closing sometimes learns the number they expected isn’t the number they can touch that day.
There’s an exception.
A borrower whose existing mortgage or other required debt eats up more than 60% of the principal limit can draw enough to pay it off, plus a little more.
Outside of that, the remaining principal limit sits untouched until year two.
3. Growing Line of Credit
Homeowners who choose a reverse mortgage line of credit get a feature other loans never offer.
Whatever a borrower leaves untouched grows larger every month, whether the home’s value rises, falls, or holds still.
That’s unusual for a loan.
A retiree who opens a line of credit early and barely touches it watches something unusual happen.
The available balance grows substantially larger by the time a need shows up years later.
Few families learn the growth even exists until a loan officer explains it after closing, once the head start is already gone.
Psst! How much do you know about where the reverse mortgage program came from? Take our quiz and see how many you can get right.
Quiz
Reverse Mortgage History IQ
Answer these questions on where the reverse mortgage program came from. We bet you can’t get them all right. Prove us wrong?
The federal law that created the reverse mortgage program insured by HUD passed in which year?
4. Life Expectancy Set-Aside
Homeowners sometimes learn at the closing table that part of their reverse mortgage never reaches them at all.
HUD's financial assessment can require a lender to hold back a set-aside from the loan.
That money covers future property taxes and homeowners insurance instead of reaching the borrower directly.
The set-aside isn't optional.
Once HUD's financial assessment triggers a set-aside, the lender holds that money back automatically, no matter what the borrower would rather do with it.
Florida's homeowners insurance premiums run highest in the nation, according to the Insurance Information Institute's state-by-state data.
That pushes the set-aside a Florida financial assessment calls for higher than the set-aside built for a borrower in a cheaper state.
A bigger set-aside means less cash at closing, even on the exact same home value.
What Non-Recourse Covers
A reverse mortgage's non-recourse protection only kicks in once the loan comes due and the home is sold, not before.
Say a Florida homeowner's loan balance reaches $420,000, but the home only appraises for $380,000 by then.
Federal Housing Administration (FHA) mortgage insurance pays the lender that $40,000 gap, and the borrower or their estate owes no more than 95% of the appraised value.
That protection covers the final payoff amount.
It doesn't cover a missed tax bill or an empty set-aside account, which the lender can still collect through the loan.
5. Florida's Extra Closing Tax
Florida families take out enough reverse mortgages to rank second in the nation for loan volume.
Florida taxes every one of them at closing in a way many other states don't.
Every mortgage recorded in Florida pays a documentary stamp tax of 35 cents per $100 of the loan, plus a separate nonrecurring intangible tax.
Origination fees come next.
A 2024 state law changed what Florida taxes.
The state now charges the stamp tax on the principal limit a borrower can access, not the larger amount a lender agrees to insure.
The change lowered the bill on closings after July 1, 2024.
Many families still assume the older, higher number applies.
6. Florida's Foreclosure Timeline
Falling behind on a reverse mortgage's property tax or insurance requirement can put the loan into default in Florida just as fast as anywhere else.
What happens after that moves slower in Florida than in many other states.
Florida requires every mortgage foreclosure, reverse or otherwise, to go through a judge instead of an out-of-court process.
That's judicial foreclosure.
The lender then sues, and Florida law gives the family roughly 20 days to respond.
The court process that follows commonly runs months before a judge signs off.
Non-judicial states move a lot faster.
Psst! Think you can spot the reverse mortgage rules from the myths? Flip these cards and find out.
7. Above HUD's Lending Limit
Florida's priciest homes can push a reverse mortgage past HUD's federal insurance program.
Once a home's value pushes the loan above HUD's HECM lending limit of $1,249,125 in 2026, a Florida lender can offer a proprietary reverse mortgage instead.
That proprietary loan is priced by the private lender, not the federal program.
Proprietary reverse mortgages aren't insured by the FHA, so the federal non-recourse protection that limits what a HECM borrower's estate can ever owe doesn't reach them.
HUD's counseling mandate applies to HECM borrowers, not to borrowers taking out a proprietary loan.
That catches buyers off guard.
Some lenders offer similar counseling voluntarily, but nothing in federal or Florida law requires it on these bigger loans.
A Florida family with a high-value coastal home can end up comparing two products that look alike in a brochure and behave nothing alike once the loan comes due.
The interest rate, the fees, and the payout options on a proprietary loan come from that one lender. They don't come from a federal formula every company in the HECM program has to follow the same way.
9 Amazon Prime Perks Floridians Pay For and Rarely Use
Amazon Prime costs $139 a year in Florida, the same fee as anywhere else in the country.
A chunk of that money buys benefits many Florida members never activate, month after month.
9 Amazon Prime Perks Floridians Pay For and Rarely Use
8 Septic and Well Rules Florida Buyers Inherit With Their House
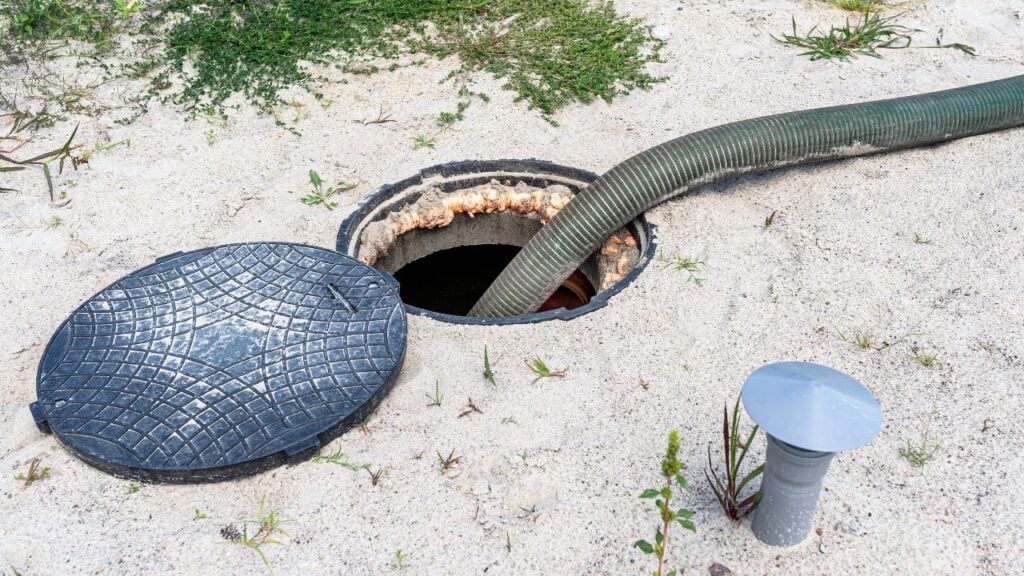
About 2.6 million septic systems serve roughly 30% of Florida's population, and every one of them comes with rules attached to the land, not the person who used to own it.
A buyer who skips the inspection can inherit years of someone else's neglect the day the deed changes hands.
8 Septic and Well Rules Florida Buyers Inherit With Their House
